

By David Wanjiru
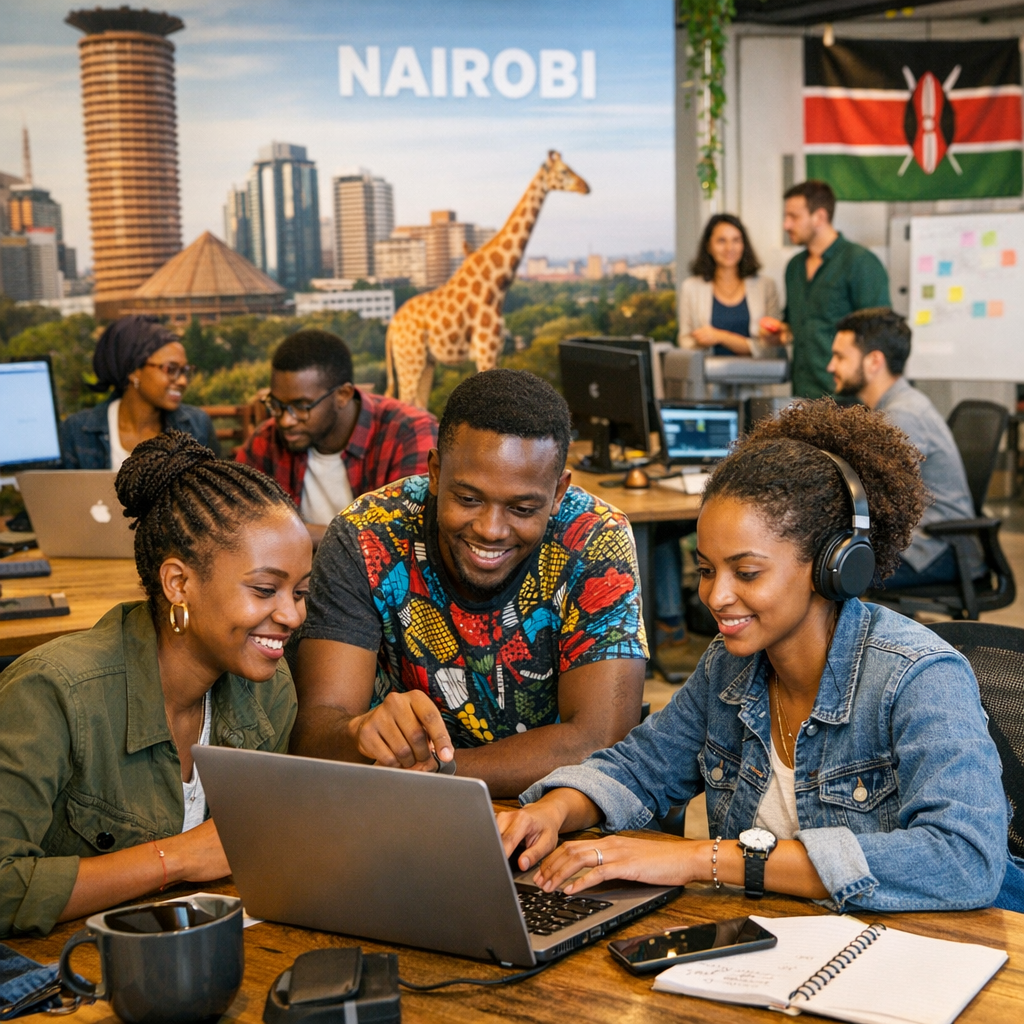
Nairobi’s startup scene is vibrant—new ventures in fintech, e-commerce, healthtech, and software services are growing fast and creating many jobs. But while many startups reach early momentum, too few scale into larger, sustainable firms. Here’s a look at what holds them back, and what could help more businesses succeed.
The scaling gap: what it looks like
Recent research shows that startups are responsible for about 80 % of new tech jobs in Kenya, yet high-growth companies make up only a small share of all startups. Many remain small or informal, limiting their ability to generate stable incomes and broader impact.
Main barriers to lasting growth
1. Finance constraints: Many founders get seed or early-stage funding, but struggle to access capital for expansion. Venture capital and angel investment tend to be limited, while debt financing is often expensive and hard to secure for startups without strong collateral.
2. Regulatory & compliance costs: Licensing, taxes, trade and export regulations are often complex and costly. High compliance burdens slow growth, especially for businesses trying to enter regional or international markets.
3. Market access & product–market fit: Some startups launch products that don’t align with customer needs, or with low market demand. Others lack the resources to do deep market research or to expand outside Nairobi, limiting their reach.
4. Infrastructure and operational hurdles: Besides internet and power costs, entrepreneurs report high costs for utilities and unreliable services. These overheads eat into profits, making scale harder.
What’s working—and where hope lies
Despite the challenges, Nairobi has strengths that many entrepreneurs are building on:
- A strong human capital base: there’s a growing pool of educated, tech-savvy workers, affordable labor, and women taking up entrepreneurial roles.
- Innovation hubs, accelerators, and support programs are more common; these provide mentorship, networking, and sometimes funding.
- Policy initiatives aimed at digital growth are under way, including efforts to expand internet access, improve digital infrastructure, and support youth-led startups.
Strategies to help Nairobi startups scale
Scaling isn’t just entrepreneurs’ work—it takes coordinated effort. These are promising strategies:
- Structured finance channels: Develop financing mechanisms that go beyond seed funding—matching grants, equity funding, or blended finance to support later-stage growth.
- Regulatory simplification: Streamline licensing, reduce costs, and harmonize trade regulations, especially under frameworks like AfCFTA, to ease regional expansion.
- Market research & customer validation: Encourage early investment in research, pilot programs, and customer discovery to ensure alignment of products/services with real needs.
- Investment in infrastructure—both digital (high-speed internet) and physical (energy, distribution networks)—to lower operating costs for growing firms.
- Building regional linkages: Mentorship, partnerships, and collaboration among startups, larger firms, government, and investors can share risks, open new markets, and scale innovation faster.
Why scale matters
Scaling startups produce higher quality jobs, contribute more to GDP, and create ripple effects in supply chains. When a startup hires more people, uses more services, and engages more suppliers, the impact stretches beyond the startup itself. That means that helping a few more startups grow can benefit whole communities and the local economy.
Looking ahead
As Nairobi continues to grow as a tech and innovation hub, the pressure is on to turn promise into performance. With better financing, clear regulations, and stronger market alignment, more startups could become scale-ups—and that could be game-changing for jobs, prosperity, and inclusive economic growth.